Theory question 101
Final Accounts of a Sole TraderSection A (compulsory)
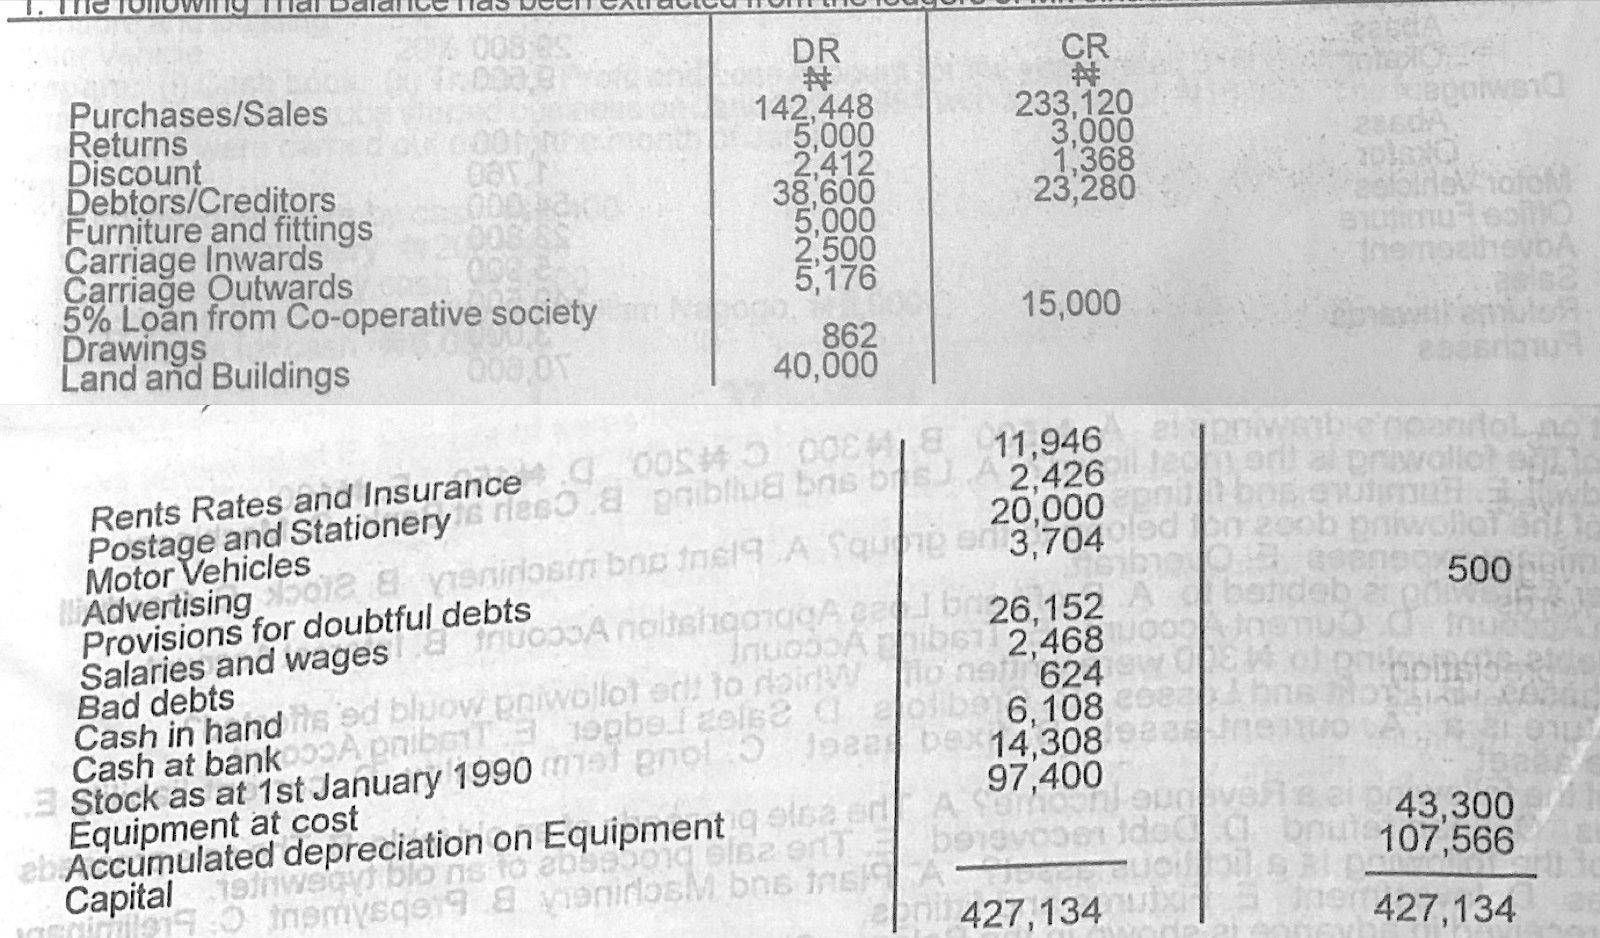
The following Trial Balance has been extracted from the ledgers of Mr. Jinadu as at 31st December 1990 (shown in the figure).
Additional Information: (a) Stock at close ₦16,442 (b) Outstanding expenses: Advertising ₦354; Salaries and wages ₦848; Interest on loan ₦750 (c) Rent, Rates and Insurance paid in advance ₦426 (d) Depreciation: Equipment 10% on cost; Furniture & Fittings 5%; Land and Building 10%; Motor Vehicles 25% (e) Salaries and wages includes ₦3,600 paid to Mr. Jinadu (f) Records of typewriter bought on Credit on 31st December 1990 for ₦10,000 have not been made in books. (g) Mr. Jinadu decided on 31st December 1990 to write off a further amount of ₦2,000 as bad debt (h) Mr. Jinadu's children consumed goods worth ₦5,500 during the year. (i) Provisions: doubtful debts 5% discount allowance 10%.
Prepare: (i) Trading, Profit and Loss Account for the year ended 31st December 1990; and (ii) A Balance Sheet as at that date.
Show the model answer
(i) Trading, Profit and Loss Account for the year ended 31 December 1990
Sales 233,120 − returns inwards 5,000 = 228,120
Purchases 142,448 + carriage inwards 2,500 − returns outwards 3,000 − goods taken for own use 5,500 = 136,448; + opening stock 14,308 − closing stock 16,442 = cost of sales 134,314
Gross profit ₦93,806; add discount received 1,368 = 95,174
Expenses: discount allowed 2,412; carriage outwards 5,176; rent, rates and insurance (11,946 − 426) 11,520; postage and stationery 2,426; advertising (3,704 + 354) 4,058; salaries and wages (26,152 − 3,600 + 848) 23,400; bad debts (2,468 + 2,000) 4,468; loan interest 750; increase in provision for doubtful debts (5% × 36,600 = 1,830 − 500) 1,330; provision for discounts (10% × 34,770) 3,477; depreciation: equipment 10% × 107,400 = 10,740, furniture 5% × 5,000 = 250, land and buildings 10% × 40,000 = 4,000, motor vehicles 25% × 20,000 = 5,000; total 79,007
Net profit ₦16,167
(ii) Balance Sheet as at 31 December 1990
Fixed assets (NBV): land and buildings 36,000; equipment 107,400 − 54,040 = 53,360; motor vehicles 15,000; furniture 4,750; total 109,110
Current assets: stock 16,442; debtors 36,600 − 1,830 − 3,477 = 31,293; prepayments 426; bank 6,108; cash 624; total 54,893
Current liabilities: creditors 23,280; typewriter creditor 10,000; accrued advertising 354, salaries 848, loan interest 750; total 35,232; working capital 19,661
Less 5% loan 15,000; net assets ₦113,771
Capital 107,566 + net profit 16,167 − drawings (862 + 3,600 + 5,500) 9,962 = ₦113,771
Salary paid to the owner and goods his family used are drawings, not business expenses.